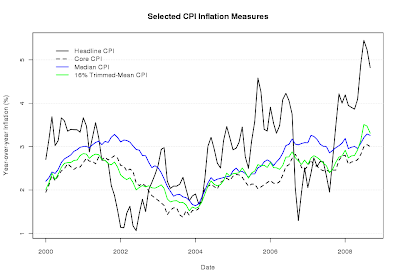
The chart below shows headline and core CPI have climbed sharply since mid-2006. Headline CPI is currently near 5% year-over-year, while all measures of core CPI are at 3%.Why, even though inflation is high and has been increasing, does the Fed consider inflation expectations to be contained? The Fed noted the fall in commodity prices, which will dampen inflation in coming months, in their October 8th statement. They also noted inflation expectations have diminished.
The following chart shows inflation expectations via the spread between the 10-year constant maturity Treasury rate and the corresponding TIPS rate. Expectations currently stand at an average of 1% per year for the next 10 years. I seriously doubt this will be realized; it's more likely a function of the current market pessimism.
Two important caveats: (1) the spread has two components - expected inflation and inflation risk premium, and (2) TIPS yields have a liquidity premium. Given the short-term nature of our comparison, neither of these caveats should be too problematic.
Wednesday, October 22, 2008
September Inflation
Posted by
Joshua Ulrich
at
10:36 PM
0
comments
Labels: Federal Reserve, Inflation
Sunday, May 18, 2008
Understated Inflation?
John Mauldin makes an excellent point regarding inflation perceptions in this week's Thoughts from the Frontline weekly e-letter. In short, consumers pay more attention to the items they buy more frequently and, currently, those are the items that are increasing in price the most.
[H]igh-frequency spending items like gasoline, food, education, and medical care make up 50% of the Consumer Price Index. These are items which we buy on a regular basis. And they are going up at a weighted average rate of 6.8%, a lot higher than the 4% for the CPI as a whole.
The 20% of the CPI which are low-frequency items like furniture, appliances, vehicles, and so on are actually falling at a -0.7% rate. Since OER (equivalent rent) is roughly 30% of CPI and is rising at 2.8%, even as home prices fall the overall rate is about 4%.
Our tendency to notice the price increases in more frequently purchased items more than the drop in less frequent expenditures is known as salience. What we see every day is more visible to us and is on our minds. And because the reality is that those prices are rising much faster than headline inflation, we tend to think inflation is understated.
Posted by
Joshua Ulrich
at
7:21 PM
2
comments
Labels: Inflation, Statistics
Tuesday, March 4, 2008
January Inflation Reports
The inflation numbers for another month are in, and the results do not look very good. The charts and brief commentary below summarize the changes.
Today Calculated Risk noted that, "inflation expectation have surged recently." They cite a Bloomberg article that charts the spread between the 5-year TIPS and the 5-year Treasury. You can find an interactive chart of the spread between those two rates on the Cleveland Fed's website.
At this point, I think it's safe to say that - contrary to what the FOMC has to say - both inflation and inflation expectations are not well contained.
Annual core PPI inflation has moved from its 2006 lows near 1% to hovering above 2% in the second half of 2007.

Core PCE inflation has jumped back above 2% and trimmed-mean PCE inflation is nearing 2.5%.

CPI inflation is worst of all; core is near 2.75%, 16% trimmed-mean is approaching 3%, and the median CPI is closing on 3.25%.
Posted by
Joshua Ulrich
at
8:45 PM
1 comments
Labels: Economy, Federal Reserve, Inflation
Friday, December 7, 2007
Non-Farm Payrolls: 12-07-2007
To quickly recapitulate the press release:
- The unemployment rate remained unchanged at 4.7%
- Employment increased 94,000 to 138,467
- Hourly earnings rose $0.08 to $17.63
However, average hourly earnings came in quite a bit above expectations (0.46% MOM versus an expected 0.30%). That doesn't bode well for inflation expectations...
Will today's stronger-than-expected employment situation change market expectations of Tuesday's Fed action? I'll update with the information from the Cleveland Fed after the market closes.
UPDATE:
Estimates of a 50 bps reduction in the Fed Funds Rate declined using either December of January options. Expectations of a 25 bps cut now stand near 60% and 70% for December and January options, respectively (in each case the remainder represents the probability of a 50 bps cut).
Posted by
Joshua Ulrich
at
7:50 AM
0
comments
Thursday, December 6, 2007
The USD and EU Inflation
Jim Jubak wrote a great piece on the woes of the USD this past Tuesday. The article focuses on inflation in the European Union affecting the USD. The entire article is worth reading, but I highlight a very significant portion below.
I'll admit I don't know what the two banks will decide Thursday and Dec. 11. But I do know what will happen if the interest-rate gap between the two currencies shrinks further:Today the ECB held their target rate at 4.0% instead of raising it, as Jim anticipated. The overnight interest rate spread between the US and EU remains 50 bps (instead of falling to 25 bps if the ECB had raised their rate). That may give the Fed a bit more breathing room to cut by 50 bps instead of 25.
- The U.S. dollar will fall, and the euro will climb.
- The price of oil, which trades in U.S. dollars, will go up again, as oil producers adjust prices so that they at least break even on the dollar's decline.
- Gold prices will climb as investors seek an alternative to the U.S. dollar as well as safety from uncertainty about the global economy and a likely bump in U.S. inflation.
- U.S. equities will rally in the days after a Federal Reserve rate cut but then give much of the gains back as overseas investors pull money out of the U.S. financial markets in response to the dollar's weakness.
As of today, the Fed Funds Futures market expects a 60% probability of a 25 bps cut and a 30% chance of a 50 bps reduction using January options (click for image). Using December options, the expectation is about 50% for both 25 and 50 bps reductions. You read that correctly, nearly a 100% expected probability of a rate cut.
Source:
The dollar's perfect storm worsens
Jim Jubak
Jubak's Journal, 12/4/2007 12:01 AM ET
http://articles.moneycentral.msn.com/Investing/JubaksJournal/TheDollarsPerfectStormWorsens.aspx
Posted by
Joshua Ulrich
at
7:45 PM
0
comments
Labels: Currency, Federal Reserve, Inflation
Sunday, November 18, 2007
October Inflation Reports
Both PPI and CPI inflation reports were released last week. PPI came in below expectations, while CPI was in line with the consensus estimate.
The chart below shows both headline and core PPI near the top of their range since 2000. Further, PPI inflation has been increasing since mid-2006. This doesn't bode well for moderating CPI inflation, if PPI leads CPI.
As expected, there was a sharp increase in YOY headline CPI inflation in October, while CPI inflation ex food and energy remained near 2.5%. In this week's Thoughts From the Frontline, John Mauldin shows YOY headline CPI inflation will remain high for the rest of 2007, due to last year's low index levels. He also describes the changes made to the CPI index in the early 1990's (substitution and hedonics).
The chart below shows two lesser-known 'core' measures of CPI inflation created by the Cleveland Fed. Both the median and trimmed-mean CPI show an increase in October. Further, Mauldin's analysis suggests we should expect these two core measure to increase in the next two months.
While the Fed doesn't have explicit inflation targets, it's believed 1-2.5% is in their comfort range for core PCE inflation. All three measures of core CPI inflation shown above are at or near 2.5%. As many have noted, this doesn't leave the Fed much room to cut thier target rate if the economy begins to slow substantially.
Posted by
Joshua Ulrich
at
7:11 PM
1 comments
Labels: Federal Reserve, Inflation
Monday, November 5, 2007
CRB Core Inflation? Hardly.
Barry Ritholtz uses the CRB "excluding food and energy" in a post today to show how high 'core' inflation is. I found the data in the post's chart at www.economagic.com. A bit of investigation into the data revealed the "ex food & energy" series to be the CRB Raw Industrials Index.
The Raw Industrials Index is composed of hides, tallow, copper scrap, lead scrap, steel scrap, zinc, tin, burlap, cotton, print cloth, wool tops, rosin, and rubber. All but hides, tallow, rosin, and rubber are contained in two other sub-groups:
- The "metals" sub-index (40% of the 'core' index) contains copper scrap, lead scrap, steel scrap, tin, and zinc.
- The "textiles and fibers" sub-index (30% of the 'core' index) is comprised of burlap, cotton, print cloth, and wool tops.
Barry has presented some good arguments against the use of core inflation in monetary policy. This is not one of them, however.
UPDATE: I should have guessed, Barry intended to be a bit over-the-top in his post...

For those interested, the R code used to create the chart is below.
require(fImport)
rawInd <- economagicImport("crb/crb12", freq="monthly")@data[-(1:7),]
rawInd$DATE <- as.Date(rawInd$DATE)
textiles <- economagicImport("crb/crb13", freq="monthly")@data[-(1:7),]
textiles$DATE <- as.Date(textiles$DATE)
metals <- economagicImport("crb/crb14", freq="monthly")@data[-(1:7),]
metals$DATE <- as.Date(metals$DATE)
plot( rawInd$DATE, rawInd$VALUE, type="l",
ylim = range( c( rawInd$VALUE, textiles$VALUE, metals$VALUE ) ),
main = "Selected CRB Indicies",
xlab = "Date", ylab = "Index Value",
lwd = 2 )
lines( textiles$DATE, textiles$VALUE, col="red" , lwd = 2 )
lines( metals$DATE, metals$VALUE, col="blue", lwd = 2 )
legend( "topleft",
legend = c("Raw Industrials","Textiles Sub Index","Metals Sub Index"),
col = c( "black", "red", "blue" ),
lty = c( 1, 1, 1 ),
lwd = c( 2, 2, 2 ),
bty = "n", inset = 0.05 )
savePlot( "Select_CRB_Indicies", type="png" )
Posted by
Joshua Ulrich
at
10:30 PM
4
comments
Labels: Inflation
Tuesday, September 18, 2007
Inconsistent Market Response to Inflation
The PPI released this morning showed headline inflation much below forecast, due to falling energy prices; but core PPI was higher than forecast. Stock futures markets rallied on the news. This is completely inconsistent with prior month's releases, when the markets rallied on relatively high headline readings because core inflation was at or below expectations.
It would seem that greater than expected PPI inflation, which also remains above the Fed's supposed comfort range of 1-2% year-over-year, would lessen the probability of the 50 bps rate cut the market's been hoping for.
UPDATE: It appears that some or all of the futures rally could be attributed to Lehman's earnings report. Even so, the PPI report didn't evoke any negative reaction.
Posted by
Joshua Ulrich
at
8:19 AM
2
comments
Labels: Federal Reserve, Inflation, Markets
Thursday, July 12, 2007
Explaining the CPI-U
This Monday's Outside the Box E-Letter by John Mauldin features a great publication from the Congressional Budget Office. To whet your appetitie, here's the introduction:
This week in Outside the Box we look at a Congressional Budget Office publication that dives us the details on how the consumer price index for all urban consumers (CPI-U) is created. This is, as the CBO posits, the best-known official measure of inflation.
The brief that follows will venture to explain the methods used to construct the CPI-U, and how and why the index's estimates of inflation might differ from a consumer's perceptions of price changes. Though I think this article may be somewhat akin to discovering what components comprise the makeup of sausages (knowledge that is usually best left undiscovered), it is useful to understand just how the inflation data is constructed. Some of the points they make are controversial, especially when it comes to "hedonic" pricing, which they refer to as "shifts in the quality of goods and services over time." This does allow for some quite subjective influence in the inflation numbers. While I will visit this topic in a later letter, it is good to know what is and is not being measured.
Posted by
Joshua Ulrich
at
8:23 PM
0
comments
Labels: Inflation
Wednesday, July 11, 2007
Bernanke Speech : 07-10-2007
This Tuesday, Ben Bernanke spoke to the NBER-sponsored Summer Institute regarding inflation expectations and inflation forecasting. On inflation expectations, Bernanke summarized recent literature focusing on defining and measuring inflation expectations, and how to use that information to forecast and control inflation.
The more interesting part of the speech concerned how the Federal Reserve Board forecasts inflation. Rather than recapitulating the most intriguing portion, I've included it below:
The Board staff employs a variety of formal models, both structural and purely statistical, in its forecasting efforts. However, the forecasts of inflation (and of other key macroeconomic variables) that are provided to the Federal Open Market Committee are developed through an eclectic process that combines model-based projections, anecdotal and other "extra-model" information, and professional judgment. In short, for all the advances that have been made in modeling and statistical analysis, practical forecasting continues to involve art as well as science.
The forecasting procedures used depend importantly on the forecast horizon. For near-term inflation forecasting--say, for the current quarter and the next--the staff relies most heavily on a disaggregated, bottom-up approach that focuses on estimating and forecasting price behavior for the various categories of goods and services that make up the aggregate price index in question. ... In making very near-term price forecasts, the staff also uses diverse information from a variety of sources, such as surveys of prices of gasoline and other important items, news reports about price-change announcements, and anecdotal information from our business contacts. Conceptually, one might think of this effort to distinguish transitory from persistent price changes as a more nuanced way of estimating the underlying inflation trend, analogous to the trend measures provided by more mechanical indicators such as trimmed-mean or weighted-median inflation rates.
An accurate forecast of very near-term inflation is important not only for its own sake but also because it provides a better "jumping-off point" for the longer-term forecast. Because inflation continues to exhibit some inertia, improved near-term forecasts translate into more-accurate longer-term projections as well.
For forecasting horizons beyond a quarter or two, detailed analyses of individual price components become less useful, and thus the staff's emphasis shifts to inflation's fundamental determinants. Food and energy inflation are forecasted separately from the core, using information from futures prices and other sources. However, forecasts of core inflation must take into account the extent to which food and energy costs are passed through to other prices.
In addition to the above, Bernanke notes that the Board uses a range of econometric models to forecast inflation at longer horizons. However, the models' estimates are not so robust as to permit sharp inferences, so the Board's long-term forecasts "inevitably reflect a substantial degree of expert judgment and the use of information not captured by the models." Finally, he turns to the Board's use of inflation expectations in forecasting inflation.
Posted by
Joshua Ulrich
at
8:07 AM
0
comments
Labels: Federal Reserve, Forecasting, Inflation
Thursday, June 14, 2007
Worthless Headline of the Day
CNN's Money site wins today's Most Worthless Headline of the Day award with this link on their homepage: Prices up in latest inflation read. Really, you don't say? Whoever wrote that must have a firm grasp of the blatantly obvious.
To be fair, that's the link displayed on their homepage, not the actual headline of the article.
Posted by
Joshua Ulrich
at
10:51 AM
0
comments
Saturday, June 9, 2007
Is Inflation Moderating?
Beginning with the March, 2007 FOMC statement, the Fed has stated that its primary concern is that inflation will not moderate as expected. The FOMC statement and minutes from the May, 2007 meeting and a CNBC interview with Chicago Fed President Michael Moskow on Friday reiterate this concern.
This suggests the inflation measure(s) the FOMC consults when determining monetary policy are at the upper end of their (collective) comfort range. The two charts below (click for larger image) show headline/core CPI and PCE inflation from 2000 to the present. Contrary to traditional headline/core inflation measures, the core inflation measures created by two regional Federal Reserve Banks show that inflation has not fallen from its levels of 2005 through early 2006.

Both year-over-year CPI and PCE headline inflation have decreased significantly from their levels of 2005 through early 2006. Compared to the same historical period, both measures of PCE core inflation have barely budged, and all measures of CPI core inflation have risen.
Both the PCE less Food & Energy and the Dallas Fed's Trimmed Mean PCE inflation measures have declined slightly since their respective peaks in late 2006. The Trimmed Mean PCE has fallen slightly less, however. Also worth noting, the spread between PCE less Food & Energy and Trimmed Mean PCE seems to be a pretty steady 20-30 bps.
CPI inflation is more interesting. CPI less Food & Energy inflation has fallen from its late-2006 peak of nearly 3% to less than 2.3% in April, 2007. However, 16% trimmed mean inflation has only fallen from 2.9% to 2.75% over the same period. Further, median CPI inflation remains near its levels (3.5%) of late 2006.
Moskow said, "The last quarter, GDP growth was very low – six-tenths of a percent. That’s history now. This quarter should be much stronger and, as we move through this year into next year, I see us moving toward potential growth, or long-term trend growth, in the economy." But if productivity continues falling and wage growth continues accelerating, I'm not sure what the Fed expects will contain inflation pressures. Then again, maybe that's why the FOMC's primary concern is inflation failing to moderate as desired...
I'll provide an update when May's CPI data come out on 6/15.
Posted by
Joshua Ulrich
at
6:24 PM
2
comments
Labels: Federal Reserve, Inflation
Thursday, June 7, 2007
Inflation and the Fed
In this morning's commentary on The Big Picture, Barry Ritholtz writes:Of course, many pundits, traders and investors -- and a goodly part of the Federal Reserve -- have convinced themselves that there really wasn't any inflation, ...
I agree with Barry regarding the many pundits, traders, and investors that have convinced themselves that there really wasn't a reason to worry about inflation (just look at the stock market action of the past few months), but I disagree that many Federal Reserve policy-makers are not concerned about inflation.
I know I've said it before on Barry's blog, but I'll say it again here: I worked at a Federal Reserve District Bank in 2004-05 as an economic research analyst - assisting the economists with their research.
There was much discussion regarding the measurement error of core CPI beginning in early 2005. That's about the time the Cleveland Fed came out with their median CPI measure, and the Dallas Fed - whose head of research is mentioned in Barry's post - created their trimmed mean PCE measure. Furthermore, the FOMC minutes have stated for some time that the main concern of the Fed is that inflation will fail to moderate as expected (i.e. inflation - by whatever measure they're now using - is above their comfort zone).
I'm not aware of the evidence Barry has seen that suggests that a good part of the Federal Reserve have convinced themselves that there is no inflation. One could argue that - given inflation data - the Fed should raise rates, but this is what is discussed/argued in FOMC meetings.
UPDATE:Here's an interesting excerpt from the Reuters article referenced in Barry's post:
On the other hand, Rosenblum said that because the Fed relies on a number of different measures of price pressure, there was not much risk the flaws in core inflation would translate into a policy mistake."The fact that core is misbehaving now because food and energy are moving in one direction instead of up and down is not all that troublesome to me because we have the good sense to look at the wide range of indicators out there," he said.
Posted by
Joshua Ulrich
at
9:01 AM
4
comments
Labels: Federal Reserve, Inflation